Growth Without Margin: Saudi Listed Healthcare at the End of Q3 2026
Growth Without Margin: Saudi Listed Healthcare at the End of Q3 2026
سوق الرعاية الصحية المدرجة في السعودية — تقرير سبتمبر 2026: نمو في الإيرادات وضغط على الهوامش
Revenues at Tadawul’s hospital groups kept rising through the first half of 2026, but profits did not follow. New hospitals are still ramping up, financing costs are higher, and 2025 one-off gains have dropped out of the comparison. By the end of September the healthcare index was about 12% below where it started the year, while the wider market was roughly flat.
Research: Tashawer Healthcare Consultancy × Operator for Health Care Services · Market data to 30 Sep 2026 · Financials to H1 2026
Five things to know this month
- Sales are up, profits are not. Across the seven hospital groups with comparable H1 figures, revenue rose 10.7% while net profit fell 7.6%. Dallah, Fakeeh Care and Almoosa reported the largest drops in profit.
- Much of the gap is timing. The companies point to pre-opening costs, depreciation on new facilities, higher finance costs, and 2025 one-off gains (land sales, fund gains, a Hajj contract) that did not repeat.
- Scale still wins. Sulaiman Al Habib grew H1 revenue 13.8% to SAR 7.44 bn and kept net profit slightly higher. Mouwasat grew both sales and profit and has the highest net margin among the hospital groups at 24.1%.
- Pharma is the bright spot. Jamjoom, SPIMACO and Avalon all grew profit in H1. Sector profit rose 24% in Q2, and the pharma index is up 1.3% for the year while the healthcare index is down 12.0%.
- September ended weakly. TASI made its lowest close since January on 29–30 September. Saudi German Health and Dallah Health touched 52-week lows, down about 50% and 40% over 12 months.
A defensive sector that has not behaved defensively
The Kingdom’s 32.2 million residents (Census 2022) and the Vision 2030 shift of care toward private and corporatised providers are still the sector’s long-term case. In 2026, though, the healthcare index has lagged the market. The regional conflict that began early in the year hit sentiment in May and June, and analysts quoted by EnterpriseAM connected the healthcare sell-off to concerns about softer hospital visits and medical inflation. At the end of H1 the sector was down 11.89% for the year, and it ended September at about the same level.
30 Jun healthcare level derived from the reported −11.89% YTD; no pharma reading was found for 30 Jun. Sources: Argaam annual, Q1 and daily market reports; EnterpriseAM.
Market access changed in February. From 1 February 2026 the CMA ended the Qualified Foreign Investor regime, so the main market is now open to all categories of foreign investor for direct purchase. Any later rise in foreign-ownership caps could bring passive index money to large-cap healthcare names.
Prices: a broad de-rating, led by the newer listings
−32.8%
−13.1%
−12.0%
−11.9%
−0.5%
+1.3%
Price change only; dividends are excluded. Sources: Argaam 1 Jan 2026 and 29–30 Sep 2026 reports.
| Company | Close 2025 | 2025 move | End-Sep 2026 | 2026 to date |
|---|---|---|---|---|
| Sulaiman Al Habib (4013) | 257.00 | −8% | 226.50 (30 Sep) | −11.9% |
| Saudi German Health (4009) | 32.56 | −53% | 28.30 (29 Sep) | −13.1% |
| Almoosa Health (4018) | 175.40 | +15% vs first-day reference | 117.80 (30 Sep) | −32.8% |
| SMC Healthcare (4019) | 18.04 | −27% vs reference | Not verified | — |
| Dallah Health (4004) | Not verified | — | 74.00 (29 Sep) | 52-week −40% |
| Care (4005) | Not verified | — | 103.30 (30 Sep) | — |
September in brief. Care was the most volatile name of the month. It closed at SAR 119.70 on 17 September after a 4.3% gain, then lost 6.9% on 30 September to finish at SAR 103.30, a 13.7% swing in under two weeks. Sulaiman Al Habib rose 3% on the last day of the month. Dallah’s price comparisons need care: the CMA has approved a 1-for-5 bonus share issue that lifts its share count from 101.6 m to 121.9 m, which will reduce the quoted price per share without changing the company’s value.
FY2025: a record revenue year
13.7 bn
4.1 bn
3.2 bn
3.1 bn
3.1 bn
1.6 bn
1.5 bn
1.2 bn
¹ Care revenue rounded to SAR 1.6 bn in the company release. Mouwasat and Saudi German Health revenues are rounded figures from EnterpriseAM.
2,401 m
822 m
538 m
464 m
318 m
302 m
290 m
242 m
Al Hammadi FY figures from StockAnalysis (secondary data); its 2025 net profit fell 28.6%.
Sulaiman Al Habib’s 2025 revenue of SAR 13.7 bn was more than three times that of the next-largest group, Dallah Health (SAR 4.07 bn, +27% after acquisitions). Net profit grew more slowly than revenue at most groups. Al Habib’s profit rose 3.7% on revenue growth of 22.4%, because new hospitals in Jeddah, Riyadh and Al Kharj are still ramping up. Mouwasat was the exception, with profit up 27.3% on revenue up 11.9%.
Revenue kept growing; profit did not
+24.0%
+13.8%
+12.2%
+11.9%
+9.6%
+8.6%
+6.8%
+4.5%
+0.7%
+26.0%
+17.7%
+7.4%
+5.8%
+1.6%
−5.7%
−34.1%
−37.6%
−54.1%
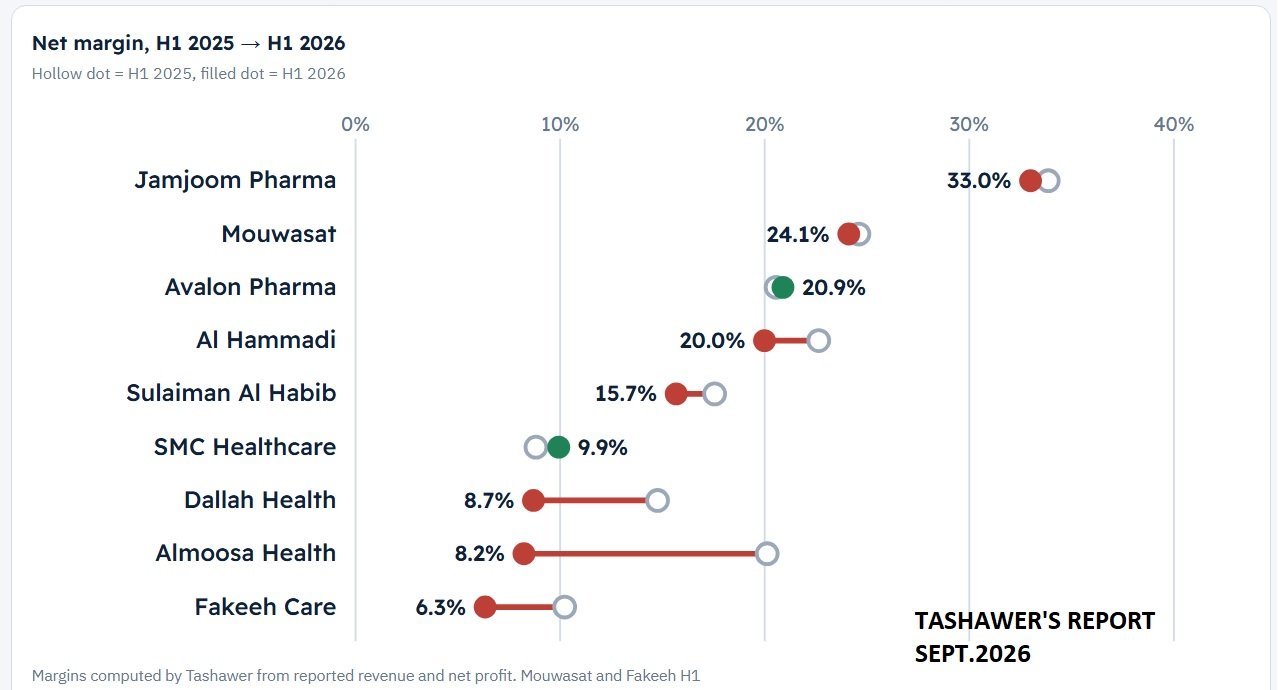
Margins computed by Tashawer from reported revenue and net profit. Mouwasat and Fakeeh H1 2025 revenue back-calculated from reported growth rates.
| Company | Revenue H1 26 (SAR m) | Change | Net profit H1 26 | Change | Net margin |
|---|---|---|---|---|---|
| Sulaiman Al Habib | 7,440 | +13.8% | 1,166.0 | +1.6% | 15.7% |
| Mouwasat | 1,710 | +9.6% | 412.4 | +7.4% | 24.1% |
| Dallah Health | 2,121 | +11.9% | 184.5 | −34.1% | 8.7% |
| Fakeeh Care | 1,520 | +0.7% | 96.3 | −37.6% | 6.3% |
| SMC Healthcare | 782 | +4.5% | 77.7 | +17.7% | 9.9% |
| Almoosa Health | 754 | +12.2% | 62.1 | −54.1% | 8.2% |
| Al Hammadi | 641 | +6.8% | 128.1 | −5.7% | 20.0% |
| Jamjoom Pharma | 927 | +8.6% | 305.8 | +5.8% | 33.0% |
| Avalon Pharma | 267 | +24.0% | 55.7 | +26.0% | 20.9% |
| SPIMACO | 916.7 | n/a | 133.5 | +29.0% | 14.6% |
| Saudi German Health | Q1: 765.2 | Q1 +4.3% | Q1: 25.7 | Q1 −83.9% | — |
Why profits fell. The explanations are company-specific. Dallah compares against 2025 real-estate fund gains of SAR 51.4 m and a SAR 12.5 m zakat reversal, and also carried SAR 15.3 m of Hajj-season costs at Mona Emergency Hospital and higher acquisition financing. Fakeeh cites depreciation at its Madinah facility, pre-opening costs at Al Awali and finance costs. Saudi German Health’s Q1 compares against a SAR 114 m land-sale gain in Q1 2025; it reported H1 revenue up and net profit down. Almoosa’s profit fell 54% while its capex more than doubled. Al Hammadi’s gross margin fell to 28.2% as outpatient visits and admissions declined.
Operator’s operating view. The pattern looks like a ramp-up curve rather than a fall in demand: patient volumes are rising at most groups (Care’s patient count +15% in H1; Mouwasat’s inpatient occupancy higher). The test for H2 is whether new beds fill fast enough to absorb their fixed staffing and depreciation costs, and whether NPHIES-driven claim processes lower denial rates or simply slow collections.
Who is spending, and how fast
73.9%
17.1%
12.7%
11.7%
4.6%
2.8%
Fakeeh FY2025 capex includes intangibles. Jamjoom reports capex/sales directly. Other groups did not disclose comparable H1 capex in the documents reviewed.
- Almoosa Health spent SAR 557 m on capex in H1 2026, equal to 74% of revenue, and reported negative operating cash flow (−SAR 1.2 m). It arranged a SAR 500 m Sharia-compliant facility with Banque Saudi Fransi.
- Al Hammadi tripled H1 capex to SAR 75 m and guides to about SAR 900 m of capex through 2030, roughly half debt-financed. Net debt rose to SAR 122 m (5.9% of equity).
- Dallah Health is recycling capital by selling its 31.21% stake in Al-Faqih & Partners to Fakeeh Care for SAR 497.98 m in cash. The General Authority for Competition cleared the deal on 11 June.
- Mouwasat opened its Yanbu hospital in Q1 2026. Care acquired Al Salam General Hospital in Riyadh. Saudi German Health plans a 194-bed hospital in Jeddah.
- Jamjoom Pharma stands apart: no debt, net cash of SAR 265.8 m, free cash flow of SAR 319 m in H1, and capex at only 2.8% of sales.
Board structure: what can be verified this month
Board-independence percentages require each director’s official classification (independent, non-executive or executive) from the latest board report. That classification was not available in the sources reviewed for this edition, so independence is not scored. The table shows board size only.
| Company | Board seats | Independent directors |
|---|---|---|
| Almoosa Health | 10 | Not yet classified |
| Sulaiman Al Habib | 9 | Not yet classified |
| Dallah Health | 9 | Not yet classified |
| Care | 9 | Not yet classified |
| Al Hammadi | 9 | Not yet classified |
| Mouwasat | 8 | Not yet classified |
| Saudi German Health | 8 | Not yet classified |
| Fakeeh Care | 8 | Not yet classified |
| SMC Healthcare | 8 | Not yet classified |
Board seats from the company profiles file in the Tashawer research database; the observation date is not stated in the file, and seats should be re-checked against each company’s latest Tadawul board announcement.
Disclosure signals this period. Every company in scope published H1 2026 results between 22 July and mid-August. Al Hammadi, Care and SMC also published earnings releases or presentations with operating KPIs such as patient volumes, occupancy and EBITDA. Mouwasat (10% cash dividend for H1) and Sulaiman Al Habib (13.3% for Q2) continued regular distributions.
What this edition can and cannot score
The research framework covers nine dimensions, including brand, social media, advertising spend, market share and HealthTech maturity. This month we publish only what is verified. A composite score would mostly reflect missing data rather than performance, so no composite ranking is published this month.
| Company | Financials | Share price | Governance | Brand & digital | Ad spend |
|---|---|---|---|---|---|
| Sulaiman Al Habib | Verified | Verified | Partial | Not assessed | Not assessed |
| Mouwasat | Verified | Not assessed | Partial | Not assessed | Not assessed |
| Dallah Health | Verified | Partial | Partial | Not assessed | Not assessed |
| Saudi German Health | Partial | Verified | Partial | Not assessed | Not assessed |
| Fakeeh Care | Verified | Not assessed | Partial | Not assessed | Not assessed |
| Care | Partial | Partial | Partial | Not assessed | Not assessed |
| Al Hammadi | Verified | Not assessed | Partial | Not assessed | Not assessed |
| Almoosa Health | Verified | Verified | Partial | Not assessed | Not assessed |
| SMC Healthcare | Verified | Partial | Partial | Not assessed | Not assessed |
| Jamjoom Pharma | Verified | Not assessed | Not assessed | Not assessed | Not assessed |
| SPIMACO | Partial | Not assessed | Not assessed | Not assessed | Not assessed |
| Avalon Pharma | Verified | Not assessed | Not assessed | Not assessed | Not assessed |
Advertising spend: public ad libraries show campaigns but not spending, so monthly budgets are reported as “Not publicly disclosed” rather than estimated. Market share: no verified market-wide revenue denominator was available, so no share percentages are published.
Scenarios for Q4 2026
- Revenue growth in high single to low double digits continues.
- Margins stabilise in Q3–Q4 as 2025 one-offs drop out of the comparison.
- The healthcare index tracks earnings and stays range-bound.
- Occupancy at new facilities rises faster than expected.
- Claims processing improves collections.
- Higher foreign-ownership caps bring index buying into large caps.
- Regional tension weighs on visits and supply costs.
- Higher leverage at expanding groups raises finance costs.
- More profit warnings lead to further de-rating.
Scenarios are analytical assumptions, not company guidance or price targets. Q3 2026 results, due October–November, will be the next test and will be covered in the October edition.
For boards and management teams
General sector recommendations drawn from the patterns above, not advice to any named company.
- Track denial rates and days sales outstanding (DSO) by payer each month, alongside NPHIES submission quality.
- Publish ramp-up KPIs (beds opened, occupancy and break-even timing) for every new facility.
- Report one-off items separately in results announcements.
- Gate further capex on measured occupancy at facilities already opened.
- Match financing to project maturity and cap leverage relative to EBITDA.
- Use staffing models that scale with occupancy.
- Use bolt-on acquisitions and asset swaps (like the Al-Faqih transaction) to sharpen regional focus.
- Invest in revenue-cycle automation and clinical analytics with measurable payback.
- Publish governance and ESG reporting that meets the requirements of foreign index investors.
How to read this report
- Universe. Main-market companies in Tadawul’s Health Care Equipment & Services and Pharma, Biotech & Life Sciences sectors with H1 2026 results available. Nomu-listed healthcare companies and pharmacy retailers classified outside the healthcare sector are not analysed in this edition.
- Periods. FY2025 is audited full-year data. H1 2026 is interim data for the six months to 30 June 2026. Market data runs to 29–30 September 2026, as dated in each row.
- Calculations. Growth rates and margins are computed by Tashawer from reported figures. Aggregates cover the seven hospital groups with both H1 periods available: Sulaiman Al Habib, Mouwasat, Dallah, Fakeeh, SMC, Almoosa and Al Hammadi.
- Conflicts. Almoosa’s H1 2025 net profit appears as SAR 135.2 m in its results release and SAR 102.9 m in Argaam’s summary. This report uses the company release. Argaam’s daily reports for 29 and 30 September give the same healthcare index close (8,682.62); it is used as the end-September level.
- Independence. This is an independent analytical publication. It does not imply that Tashawer or Operator audited, endorsed or advised any company analysed. Nothing in this report is investment advice or a recommendation to buy or sell any security.
Source register
- Saudi Exchange – Dallah Health H1 2026 financial indicators
- Saudi Exchange – Dallah Health FY2025 financial indicators
- Saudi Exchange – Fakeeh Care FY2025 results
- Saudi Exchange – Almoosa Health H1 2026 results
- Saudi Exchange – SMC Healthcare H1 2026 results
- Saudi Exchange – Avalon Pharma H1 2026 results
- Saudi Exchange – Jamjoom Pharma H1 2026 results
- Al Hammadi – 2Q 2026 earnings release
- Care – 2Q 2026 results press release
- Sahm Capital – Sulaiman Al Habib FY2025 results (15 Feb 2026)
- Jawlah – Sulaiman Al Habib H1 2026 results (26 Jul 2026)
- Decypha/Mubasher – Mouwasat H1 2026 (3 Aug 2026)
- Decypha/Mubasher – Dallah Health H1 2026 (4 Aug 2026)
- Decypha/Mubasher – Fakeeh Care H1 2026 (9 Aug 2026)
- Decypha/Mubasher – Almoosa Health H1 2026 (10 Aug 2026)
- Decypha/Mubasher – SPIMACO Q2 and H1 2026 (30 Jul 2026)
- Decypha/Mubasher – Saudi German Health Q1 2026 (4 May 2026)
- Argaam – Saudi German Health CEO on Q1 2026 results
- MarketScreener – Saudi German Health H1 net profit falls (11 Aug 2026)
- EnterpriseAM – Sulaiman Al Habib 2025 earnings
- EnterpriseAM – Mouwasat 2025 earnings
- EnterpriseAM – Jamjoom Pharma and Saudi German Health 2025 earnings
- EnterpriseAM – TASI in H1 2026 and the regional war
- Asharq Al-Awsat – Saudi healthcare firms’ Q1 2026 profit
- Argaam – Sector profits Q2 2026
- Argaam – TASI 2025 annual performance (1 Jan 2026)
- Argaam – TASI Q1 2026 performance (1 Apr 2026)
- Argaam – Market report 17 Sep 2026
- Argaam – Market report 29 Sep 2026
- Argaam – Market report 30 Sep 2026
- Argaam – 52-week lows, 29 Sep 2026
- Argaam – Dallah and Fakeeh antitrust clearance for Al-Faqih deal
- Argaam – CMA approves Dallah Health bonus shares
- Argaam – Mouwasat H1 2026 dividend
- Argaam – Sulaiman Al Habib Q2 2026 dividend
- GLMM – Saudi Census 2022 population by region
© 2026 Tashawer – all rights reserved. TASHAWER – HEALTH ALLIANCE | تشاور – التحالف الصحي · THE FALCON VIEW | رؤية الصقر. Research cut-off: 30 September 2026. Next edition: October 2026.
Displaying saudi-listed-healthcare-sept-2026-wordpress-code.txt.